सभी किताबें

पेशेवर

ऐप्स परिचय Coach लॉग इन पढ़ना शुरू करें

Quantitative Finance · शब्दावली

Forward measure क्या है?

Definition 5.7 Quantitative Methods · अध्याय 5 — Girsanov and Changes of Numeraire

The forward measure QT\mathbb Q^T for maturity TT is the equivalent martingale measure for the numeraire P(t,T)P(t, T), the zero-coupon bond maturing at TT.

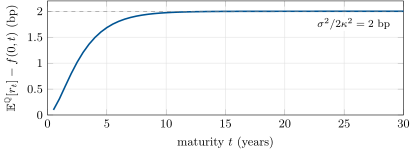
Expected short rate under the risk-neutral measure minus the instantaneous forward rate, which is the expected short rate under the forward measure of the same maturity, for the chapter’s Ornstein–Uhlenbeck short rate. The gap, 2B(t)2/2, is the price of the bond’s convexity. Data: closed forms, the chapter’s tutorial.
Figure 5.3. Expected short rate under the risk-neutral measure minus the instantaneous forward rate, which is the expected short rate under the forward measure of the same maturity, for the chapter’s Ornstein–Uhlenbeck short rate. The gap, σ2B(t)2/2\sigma^2B(t)^2/2, is the price of the bond’s convexity. Data: closed forms, the chapter’s tutorial.
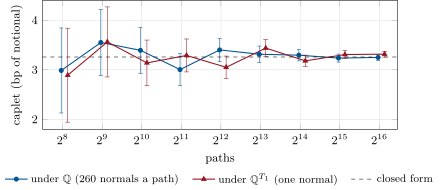
The caplet by Monte Carlo under the risk-neutral measure (weekly steps, money-market discounting) and under the fixing-date forward measure, with ± 2 standard errors, against the closed form 3.26 bp. At equal numbers of paths the errors are the same; the forward-measure path costs one normal instead of 260. Data: the chapter’s tutorial, seeded.
Figure 5.4. The caplet by Monte Carlo under the risk-neutral measure (weekly steps, money-market discounting) and under the fixing-date forward measure, with ±2\pm 2 standard errors, against the closed form 3.26 bp. At equal numbers of paths the errors are the same; the forward-measure path costs one normal instead of 260. Data: the chapter’s tutorial, seeded.
अध्याय में पढ़ें →