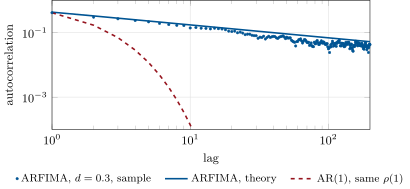
Fractional Brownian motion with Hurst exponent is the centred Gaussian process with and (Mandelbrot and Van Ness, 1968). For it is Brownian motion; for its increments are positively correlated with power-law decay, for negatively.
 المدرب
تسجيل الدخول
ابدأ القراءة
Quantitative Finance · المسرد
Fractional Brownian motion with Hurst exponent is the centred Gaussian process with and (Mandelbrot and Van Ness, 1968). For it is Brownian motion; for its increments are positively correlated with power-law decay, for negatively.