
All books

Professional

Apps About Coach Log in Start reading

Quantitative Finance · Glossary

What is Full revaluation, revaluation grid?

Also known as: full revaluation · revaluation grid

Definition 29.2 Rates, Credit, XVA and Risk · Chapter 29 — Build: A Risk Engine

Full revaluation reprices every position with its pricing model in every scenario. A revaluation grid reprices each position on a small grid of shifts of each risk factor it depends on, once, and computes each scenario’s P&L by interpolating on the grid and adding the factors’ contributions.
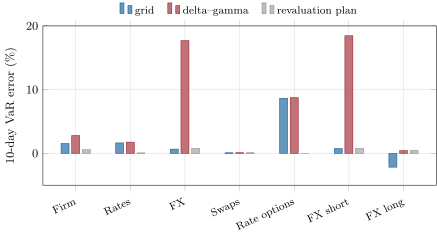
Relative error of the ten-day 99% VaR against full revaluation, by node of the hierarchy. Delta–gamma fails on the short-dated options, whose gamma changes over a ten-day move; both approximations fail on the swaptions, whose value depends on the product of moves at different pillars; the plan that revalues the swaptions in full stays within 0.76% everywhere. Data: the chapter’s tutorial, on US Treasury yields and ECB reference rates.
Figure 29.2. Relative error of the ten-day 99% VaR against full revaluation, by node of the hierarchy. Delta–gamma fails on the short-dated options, whose gamma changes over a ten-day move; both approximations fail on the swaptions, whose value depends on the product of moves at different pillars; the plan that revalues the swaptions in full stays within 0.76% everywhere. Data: the chapter’s tutorial, on US Treasury yields and ECB reference rates.
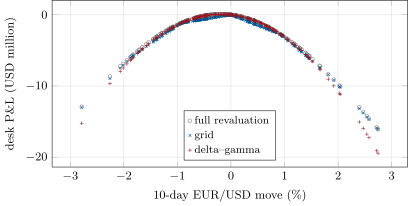
P&L of the short-dated FX desk (mostly sold options) in each ten-day scenario, against the scenario’s EUR/USD move. The grid sits on the full revaluation; the delta–gamma parabola overstates the losses of large moves. Data: the chapter’s tutorial.
Figure 29.3. P&L of the short-dated FX desk (mostly sold options) in each ten-day scenario, against the scenario’s EUR/USD move. The grid sits on the full revaluation; the delta–gamma parabola overstates the losses of large moves. Data: the chapter’s tutorial.

Examples

Example 29.3 (Cost and error on a 1 000-trade book)

The test book holds 600 swaps, 200 swaptions and 200 EUR/USD options, 89 of them expiring within a month (71 sold). Full revaluation under 250 scenarios takes 251 000 pricing calls, the grid 50 200 and delta–gamma 17 400. With one-day scenarios, the grid’s 99% VaR is within 1.59% of full revaluation at every node and delta–gamma within 0.74%. With ten-day scenarios, delta–gamma overstates the short-dated FX desk’s VaR by 18.45%, and both approximations miss the rate options’ VaR by more than 8.6% (Figure 29.2).

Example 29.6 (Ten-day risk by node)

With full revaluation, the firm’s ten-day 99% VaR is USD 53.53 million and its 97.5% ES 50.89 million. The FX business’s own ES is 14.63 million, but its Euler contribution to the firm’s is only 3.56 million, against 47.34 million for rates: the firm’s tail is a rates tail. The short-dated FX desk’s VaR, 14.58 million, breaches its limit of 12 million, and the engine flags it.

Read in context →