
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Full revaluation, revaluation grid؟

يُعرف أيضًا باسم: full revaluation · revaluation grid

Definition 29.2 Rates, Credit, XVA and Risk · الفصل 29 — Build: A Risk Engine

Full revaluation reprices every position with its pricing model in every scenario. A revaluation grid reprices each position on a small grid of shifts of each risk factor it depends on, once, and computes each scenario’s P&L by interpolating on the grid and adding the factors’ contributions.
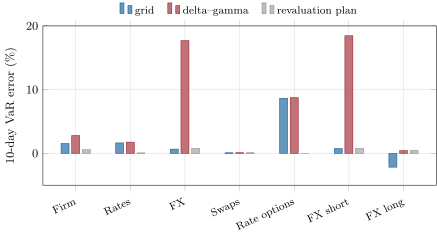
Relative error of the ten-day 99% VaR against full revaluation, by node of the hierarchy. Delta–gamma fails on the short-dated options, whose gamma changes over a ten-day move; both approximations fail on the swaptions, whose value depends on the product of moves at different pillars; the plan that revalues the swaptions in full stays within 0.76% everywhere. Data: the chapter’s tutorial, on US Treasury yields and ECB reference rates.
Figure 29.2. Relative error of the ten-day 99% VaR against full revaluation, by node of the hierarchy. Delta–gamma fails on the short-dated options, whose gamma changes over a ten-day move; both approximations fail on the swaptions, whose value depends on the product of moves at different pillars; the plan that revalues the swaptions in full stays within 0.76% everywhere. Data: the chapter’s tutorial, on US Treasury yields and ECB reference rates.
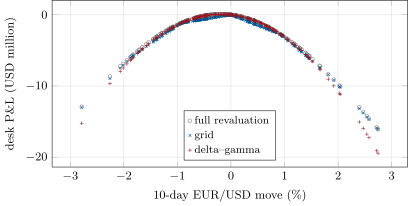
P&L of the short-dated FX desk (mostly sold options) in each ten-day scenario, against the scenario’s EUR/USD move. The grid sits on the full revaluation; the delta–gamma parabola overstates the losses of large moves. Data: the chapter’s tutorial.
Figure 29.3. P&L of the short-dated FX desk (mostly sold options) in each ten-day scenario, against the scenario’s EUR/USD move. The grid sits on the full revaluation; the delta–gamma parabola overstates the losses of large moves. Data: the chapter’s tutorial.

أمثلة

Example 29.3 (Cost and error on a 1 000-trade book)

The test book holds 600 swaps, 200 swaptions and 200 EUR/USD options, 89 of them expiring within a month (71 sold). Full revaluation under 250 scenarios takes 251 000 pricing calls, the grid 50 200 and delta–gamma 17 400. With one-day scenarios, the grid’s 99% VaR is within 1.59% of full revaluation at every node and delta–gamma within 0.74%. With ten-day scenarios, delta–gamma overstates the short-dated FX desk’s VaR by 18.45%, and both approximations miss the rate options’ VaR by more than 8.6% (Figure 29.2).

Example 29.6 (Ten-day risk by node)

With full revaluation, the firm’s ten-day 99% VaR is USD 53.53 million and its 97.5% ES 50.89 million. The FX business’s own ES is 14.63 million, but its Euler contribution to the firm’s is only 3.56 million, against 47.34 million for rates: the firm’s tail is a rates tail. The short-dated FX desk’s VaR, 14.58 million, breaches its limit of 12 million, and the engine flags it.

اقرأ في الفصل →