 Coach
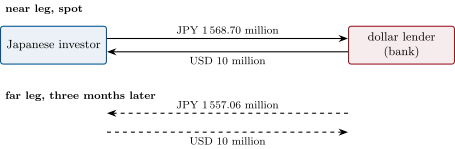
An FX swap is a pair of opposite exchanges of the same amount of one currency: a near leg, usually at spot, and a far leg at a forward date, the two rates differing by the forward points. Tom-next is the one-day swap from the next business day (tomorrow) to the day after (next), with which positions are rolled from one spot date to the next.
Examples
Example 16.3 (Three-month USDJPY)
With USDJPY at 156.87, a dollar rate of 3.68% (actual/360) and a yen rate of 0.977% (actual/365), the 91-day forward by Equation 16.1 is 155.8028: forward points of pips of 0.01 yen. A basis of basis points on the yen leg, as defined below, lowers it to 155.7059, pips. The one-day tom-next points are .