
Todos los libros

Profesional

Apps Acerca de Coach Iniciar sesión Empezar a leer

Quantitative Finance · Glosario

¿Qué es FX swap, tom-next?

También llamado: FX swap · tom-next

Definition 16.4 Markets II: Rates, FX and Credit · Capítulo 16 — FX Swaps, Forwards and the Cross-Currency Basis

An FX swap is a pair of opposite exchanges of the same amount of one currency: a near leg, usually at spot, and a far leg at a forward date, the two rates differing by the forward points. Tom-next is the one-day swap from the next business day (tomorrow) to the day after (next), with which positions are rolled from one spot date to the next.
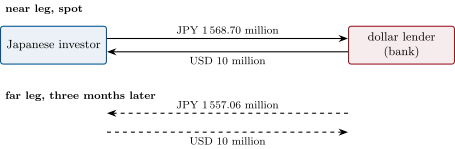
A three-month USDJPY FX swap at the forward of  with a -25 basis-point basis. The investor borrows dollars and lends yen, each loan secured by the other; it gets back JPY 11.64 million fewer than it paid, the price of the dollars. Illustrative.
Figure 16.1. A three-month USDJPY FX swap at the forward of Example 16.3 with a −25-25 basis-point basis. The investor borrows dollars and lends yen, each loan secured by the other; it gets back JPY 11.64 million fewer than it paid, the price of the dollars. Illustrative.

Ejemplos

Example 16.3 (Three-month USDJPY)

With USDJPY at 156.87, a dollar rate of 3.68% (actual/360) and a yen rate of 0.977% (actual/365), the 91-day forward by Equation 16.1 is 155.8028: forward points of −106.7-106.7 pips of 0.01 yen. A basis of −25-25 basis points on the yen leg, as defined below, lowers it to 155.7059, −116.4-116.4 pips. The one-day tom-next points are −1.18-1.18.

Leer en el capítulo →