सभी किताबें

पेशेवर

ऐप्स परिचय Coach लॉग इन पढ़ना शुरू करें

Quantitative Finance · शब्दावली

Gamma flip level क्या है?

Definition 6.2 Strategies II: Volatility, Relative Value, Macro and the Bank Desks · अध्याय 6 — Zero-Day Options and Dealer-Gamma Flows

The gamma flip level is the index level at which an estimate of the dealers’ total gamma changes sign: above it dealers are estimated long gamma, below it short.
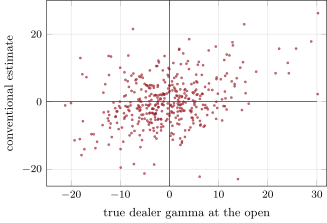
The dealers’ true total gamma at the open against the conventional estimate from open interest (dealers long every call, short every put), first 400 of the 2 000 synthetic days, in the model’s units. Points in the upper-left and lower-right quadrants are days whose sign the estimate gets wrong: 44% of all days. Data: s2_gammaflow.days.
Figure 6.1. The dealers’ true total gamma at the open against the conventional estimate from open interest (dealers long every call, short every put), first 400 of the 2 000 synthetic days, in the model’s units. Points in the upper-left and lower-right quadrants are days whose sign the estimate gets wrong: 44% of all days. Data: s2_gammaflow.days.
अध्याय में पढ़ें →
