
Alle boeken

Professioneel

Apps Over Coach Inloggen Begin met lezen

Quantitative Finance · Begrippenlijst

Wat is Hayashi–Yoshida estimator, refresh-time sampling?

Ook bekend als: Hayashi--Yoshida estimator · refresh-time sampling

Definition 21.8 Quantitative Methods · Hoofdstuk 21 — High-Frequency Econometrics

The Hayashi–Yoshida estimator (Hayashi and Yoshida, 2005) of the covariation sums the products of all pairs of returns, one from each asset, whose observation intervals overlap, with no interpolation. Refresh-time sampling samples both assets at the first time each has traded since the previous sampling time.
The Epps effect: realised correlation of two simulated stocks (true correlation 0.6) that trade at independent Poisson times, on average every 5 and 15 seconds, against the sampling interval, averaged over forty days; and the Hayashi–Yoshida estimate from all the trades (0.594). Data: the chapter’s tutorial, seeded.
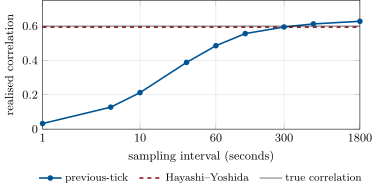
Figure 21.4. The Epps effect: realised correlation of two simulated stocks (true correlation 0.6) that trade at independent Poisson times, on average every 5 and 15 seconds, against the sampling interval, averaged over forty days; and the Hayashi–Yoshida estimate from all the trades (0.594). Data: the chapter’s tutorial, seeded.
Lees in het hoofdstuk →