 Coach
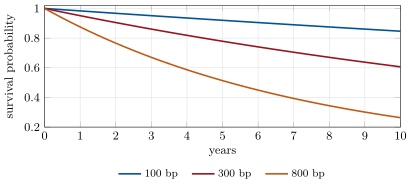
The hazard rate of a reference entity is its instantaneous rate of default at time given survival to : the probability of default in , given no default before , is . The survival probability to is , which is for a flat hazard rate.
Exemples
Example 23.6 (Two quotes, two conventions)
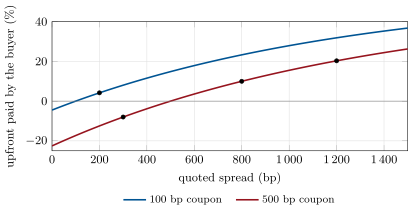
With a flat rate of 4% and a recovery of 40%, the five-year risky annuity is 4.332 at a spread of 100 basis points and 4.165 at 200. An investment-grade name quoted at 200 basis points, on the 100 basis point coupon, costs the buyer upfront, USD 416 000 on USD 10 million. A high-yield name quoted at 300 basis points on the 500 coupon pays the buyer 8.01% upfront; at 800 the buyer pays 9.98%, and at 1 200, 20.28%. Investment-grade names are quoted in spread, high-yield names in points upfront.