جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Huber loss, median absolute deviation؟

يُعرف أيضًا باسم: Huber loss · median absolute deviation

Definition 15.3 Quantitative Methods · الفصل 15 — Robust Statistics and Heavy Tails

The Huber loss with threshold cc is ρc(r)=r2/2\rho_c(r) = r^2/2 for ∣r∣≤c|r| \le c and c∣r∣−c2/2c|r| - c^2/2 otherwise; the Huber M-estimator of location minimises ∑iρc((xi−μ)/s)\sum_i\rho_c((x_i - \mu)/s) for a robust scale ss, so its estimating function ψc(r)=max⁡(−c,min⁡(c,r))\psi_c(r) = \max(-c, \min(c, r)) is bounded (Huber, 1964). The median absolute deviation is MAD=1.4826 medi∣xi−medjxj∣\mathrm{MAD} = 1.4826\,\mathrm{med}_i|x_i - \mathrm{med}_jx_j|, the constant making it consistent for the standard deviation of a normal law.

Three estimates of the daily volatility of EUR/USD from the 250 reference-rate returns to 23 September 2026, when the log price of 24 March 2026 carries an error. The dot is the transposed-digit print 1.5172 for 1.1572 (an error of 27.1%): standard deviation 2.43% instead of 0.34%, MAD 0.279% instead of 0.275%, Q_n 0.305% instead of 0.300%. Data: ECB euro reference rates (source: ECB statistics).
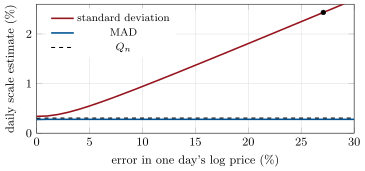
Figure 15.1. Three estimates of the daily volatility of EUR/USD from the 250 reference-rate returns to 23 September 2026, when the log price of 24 March 2026 carries an error. The dot is the transposed-digit print 1.5172 for 1.1572 (an error of 27.1%): standard deviation 2.43% instead of 0.34%, MAD 0.279% instead of 0.275%, QnQ_n 0.305% instead of 0.300%. Data: ECB euro reference rates (source: ECB statistics).
اقرأ في الفصل →