 Coach
The implied–realised spread of an option position is the difference between the implied volatility at which it was traded and the volatility subsequently realised by the underlying over its life, the quantity a delta-hedged position is a bet on, and only on average.
Ejemplos
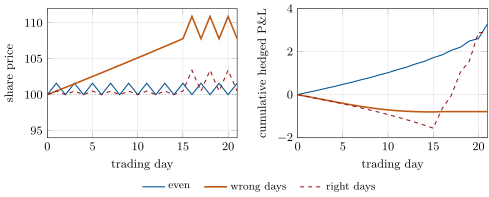
Example 25.3 (Same volatility, different days)
A 21-day at-the-money straddle on a share at 100, bought at 18 volatility (premium 4.15), hedged daily at 18. Three paths all realise exactly 25%:
- even: a move of every day, up and down in turn. The straddle makes 3.28;
- the wrong days: fifteen days of (7.9% realised), which take the share to 107.8, then six days of (45% realised). The quiet weeks lose 0.80 while the gamma is large; the wild week, far from the strike, makes 0.02. The total is ;
- the right days: fifteen days of at the strike, then the same wild week there, with the most gamma of the month. The straddle makes 2.87.
The cash-gamma sum reproduces these within a few tenths (3.05, , 3.03): the rest is the higher-order terms of the large moves (Figure 25.1).