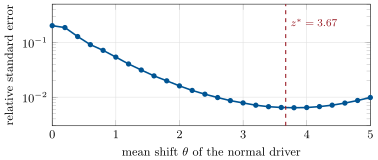
Importance sampling draws from a density instead of and averages , the payoff times the likelihood ratio (a Radon–Nikodym derivative); it is unbiased whenever where .
 Coach
Inloggen
Begin met lezen
Quantitative Finance · Begrippenlijst
Importance sampling draws from a density instead of and averages , the payoff times the likelihood ratio (a Radon–Nikodym derivative); it is unbiased whenever where .