Semua buku

Profesional

Aplikasi Tentang Pelatih Masuk Mulai membaca

Quantitative Finance · Glosarium

Apa itu Index backtest decay?

Definition 27.3 Strategies II: Volatility, Relative Value, Macro and the Bank Desks · Bab 27 — Quantitative Investment Strategies

Index backtest decay is the fall from the Sharpe ratio of a strategy index’s pre-launch backtest to that of its live, after-fee returns, measured across launched indices.
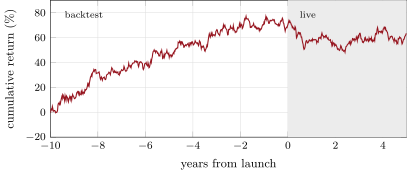
One synthetic product team’s best index: cumulative sum of daily returns at a 10% volatility target over its ten-year backtest and its first five live years after fees and leakage (shaded). Data: s2_qis.path.
Figure 27.1. One synthetic product team’s best index: cumulative sum of daily returns at a 10% volatility target over its ten-year backtest and its first five live years after fees and leakage (shaded). Data: s2_qis.path.
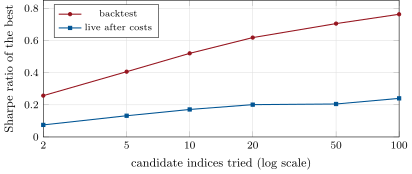
The best of N candidate indices: mean backtest Sharpe ratio and mean live Sharpe ratio after fees and leakage, over 2 000 synthetic product teams, against the number of candidates tried. Data: s2_qis.complexity.
Figure 27.2. The best of NN candidate indices: mean backtest Sharpe ratio and mean live Sharpe ratio after fees and leakage, over 2 000 synthetic product teams, against the number of candidates tried. Data: s2_qis.complexity.
Baca dalam konteks →