Todos os livros

Profissional

Apps Sobre Coach Entrar Começar a ler

Quantitative Finance · Glossário

O que é Integrated variance, realised variance?

Também chamado de: integrated variance · realised variance

Definition 18.6 Quantitative Methods · Capítulo 18 — Volatility Models

If the log price follows dXt=μt dt+σt dWtdX_t = \mu_t\,dt + \sigma_t\,dW_t, the integrated variance of day tt is IVt=∫t−1tσs2 ds\mathrm{IV}_t = \int_{t-1}^t\sigma_s^2\,ds. The realised variance is the sum of the day’s squared intraday returns, RVt=∑j=1mrt,j2\mathrm{RV}_t = \sum_{j=1}^m r_{t,j}^2 over mm intervals.

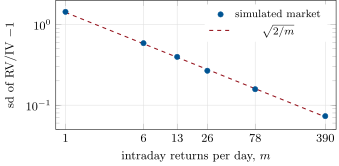
Relative error of realised variance as a measure of integrated variance, against the number of intraday returns (1 = daily squared return, 78 = five minutes over 6.5 hours, 390 = one minute), in a simulated three-component stochastic-volatility market without microstructure noise, and the theory √2/m. Data: the chapter’s tutorial, seeded.
Figure 18.4. Relative error of realised variance as a measure of integrated variance, against the number of intraday returns (1 = daily squared return, 78 = five minutes over 6.5 hours, 390 = one minute), in a simulated three-component stochastic-volatility market without microstructure noise, and the theory 2/m\sqrt{2/m}. Data: the chapter’s tutorial, seeded.
Ler no capítulo →