Todos los libros

Profesional

Apps Acerca de Coach Iniciar sesión Empezar a leer

Quantitative Finance · Glosario

¿Qué es Interior-point method?

Definition 23.12 Quantitative Methods · Capítulo 23 — Convex Optimisation

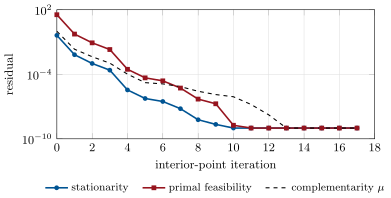
An interior-point method follows the central path: it applies Newton’s method to the KKT conditions with complementary slackness relaxed to sizi=μs_iz_i = \mu for slacks ss and multipliers zz, keeping both strictly positive, and drives μ\mu to zero.

Convergence of the firm’s interior-point solver on the long-short portfolio (1 000 variables): the norms of the stationarity and feasibility residuals and the average complementarity  at each Mehrotra iteration, floored at 10-9 (below it, the last digits depend on the order of floating-point operations). Data: the chapter’s tutorial, seeded.
Figure 23.4. Convergence of the firm’s interior-point solver on the long-short portfolio (1 000 variables): the norms of the stationarity and feasibility residuals and the average complementarity μ\mu at each Mehrotra iteration, floored at 10−910^{-9} (below it, the last digits depend on the order of floating-point operations). Data: the chapter’s tutorial, seeded.
Leer en el capítulo →