
Alle boeken

Professioneel

Apps Over Coach Inloggen Begin met lezen

Quantitative Finance · Begrippenlijst

Wat is Intermarket signal, slow diffusion?

Ook bekend als: intermarket signal · slow diffusion

Definition 22.1 Strategies I: Equities and Futures · Hoofdstuk 22 — Cross-Asset Lead–Lag

An intermarket signal predicts the returns of one market from the past returns of another that reflects the same fundamentals sooner, such as a commodity for its producers or a bond market for rate-sensitive stocks. Slow diffusion is the mechanism behind it: information reaches the prices of different assets at different speeds because investors specialise, attend to few markets, or face costs of trading, so prices that should move together move in sequence.
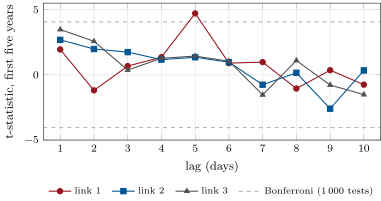
The lag-by-lag scan on the synthetic industries and commodities, first five years: the t-statistic of each planted link’s lagged correlation at lags of 1 to 10 days, against the Bonferroni threshold for 1 000 tests. Each link spreads a commodity’s return over the next five days. Data: s1_xasset.daily.
Figure 22.1. The lag-by-lag scan on the synthetic industries and commodities, first five years: the t-statistic of each planted link’s lagged correlation at lags of 1 to 10 days, against the Bonferroni threshold for 1 000 tests. Each link spreads a commodity’s return over the next five days. Data: s1_xasset.daily.
Lees in het hoofdstuk →