
Todos los libros

Profesional

Apps Acerca de Coach Iniciar sesión Empezar a leer

Quantitative Finance · Glosario

¿Qué es Intraday mean reversion?

Definition 25.2 Strategies I: Equities and Futures · Capítulo 25 — Short-Term Futures Strategies

Intraday mean reversion is the tendency of short intraday price moves to be partly reversed within minutes, from bid–ask bounce and liquidity providers’ inventory; a mean-reversion strategy fades moves larger than a threshold and exits after a fixed holding time.
The intraday fade on ten years of synthetic one-minute sessions: Sharpe ratios before and after costs of fading five-minute moves beyond a threshold and holding five minutes. The planted bounce is real; half the quoted spread of Book 7’s tape, each way, is larger. Data: s1_futures.fade_table.
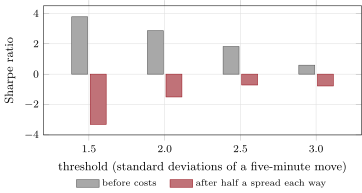
Figure 25.1. The intraday fade on ten years of synthetic one-minute sessions: Sharpe ratios before and after costs of fading five-minute moves beyond a threshold and holding five minutes. The planted bounce is real; half the quoted spread of Book 7’s tape, each way, is larger. Data: s1_futures.fade_table.
Leer en el capítulo →