 Coach
Intraday mean reversion is the tendency of short intraday price moves to be partly reversed within minutes, from bid–ask bounce and liquidity providers’ inventory; a mean-reversion strategy fades moves larger than a threshold and exits after a fixed holding time.
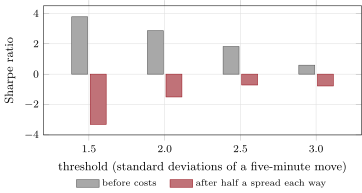
s1_futures.fade_table.