
Alle boeken

Professioneel

Apps Over Coach Inloggen Begin met lezen

Quantitative Finance · Begrippenlijst

Wat is Jarrow–Yildirim model?

Ook bekend als: Jarrow--Yildirim model

Definition 11.1 Rates, Credit, XVA and Risk · Hoofdstuk 11 — Inflation Derivatives

The Jarrow–Yildirim model (2003) models the nominal short rate and the real short rate as two Hull–White processes and the index as a lognormal exchange rate between them: dI/I=(nt−rtR) dt+σI dWIdI/I = (n_t-r^R_t)\,dt+\sigma_I\,dW_I under the nominal measure, with correlations between the three drivers. As with a foreign short rate seen from home (the quanto adjustment of One Quant Book 5, chapter 17), the real rate acquires the drift −ρ σRσI-\rho\,\sigma_R\sigma_I under the nominal measure, ρ\rho the correlation of the real rate with the index.
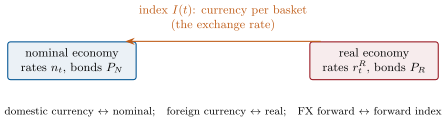
The foreign-currency analogy behind inflation models: real money is a foreign currency whose exchange rate is the price index, so the machinery of cross-currency pricing, including quanto drifts, carries over.
Figure 11.1. The foreign-currency analogy behind inflation models: real money is a foreign currency whose exchange rate is the price index, so the machinery of cross-currency pricing, including quanto drifts, carries over.
Lees in het hoofdstuk →