Coach
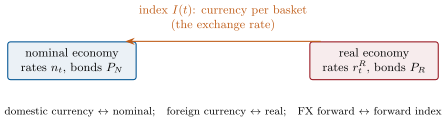
The Jarrow–Yildirim model (2003) models the nominal short rate and the real short rate as two Hull–White processes and the index as a lognormal exchange rate between them: under the nominal measure, with correlations between the three drivers. As with a foreign short rate seen from home (the quanto adjustment of One Quant Book 5, chapter 17), the real rate acquires the drift under the nominal measure, the correlation of the real rate with the index.