
Alle boeken

Professioneel

Apps Over Coach Inloggen Begin met lezen

Quantitative Finance · Begrippenlijst

Wat is Jump-diffusion, semimartingale?

Ook bekend als: jump-diffusion · semimartingale

Definition 6.3 Quantitative Methods · Hoofdstuk 6 — Jump Processes

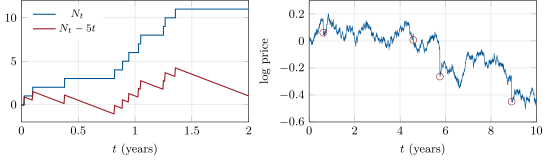
A jump-diffusion is Xt=X0+∫0tμs ds+∫0tσs dWs+JtX_t = X_0 + \int_0^t\mu_s\,ds + \int_0^t\sigma_s\,dW_s + J_t, with JJ a compound Poisson process (finitely many jumps on bounded intervals). A semimartingale is a process that is a local martingale plus an adapted process of finite variation, both càdlàg: the widest class of integrators for which stochastic integrals and Itô’s formula work.
Left: a Poisson process with rate 5 a year and its compensated martingale N_t - 5t. Right: ten years of the chapter’s calibrated jump-diffusion (daily steps; jumps at rate 0.5 a year with mean -11.1\%, marked), with the drift that makes the mean daily return zero. Data: the chapter’s tutorial, seeded.
Figure 6.1. Left: a Poisson process with rate 5 a year and its compensated martingale Nt−5tN_t - 5t. Right: ten years of the chapter’s calibrated jump-diffusion (daily steps; jumps at rate 0.5 a year with mean −11.1%-11.1\%, marked), with the drift that makes the mean daily return zero. Data: the chapter’s tutorial, seeded.
Lees in het hoofdstuk →