Coach
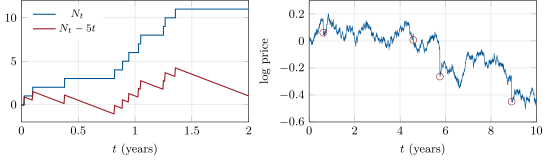
A jump-diffusion is , with a compound Poisson process (finitely many jumps on bounded intervals). A semimartingale is a process that is a local martingale plus an adapted process of finite variation, both càdlàg: the widest class of integrators for which stochastic integrals and Itô’s formula work.