 Coach
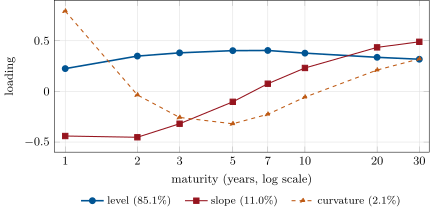
For a curve sampled at maturities, let be the first three eigenvectors of the covariance of its daily changes (with ). The level factor has loadings of one sign, the slope factor changes sign once, from short to long maturities, and the curvature factor changes sign twice. The move of day has score on factor , and the factors are uncorrelated by construction.
उदाहरण
Example 3.8 (Ten years of Treasury moves)
Over the 2 681 daily changes of the US Treasury par curve from January 2016 to September 2026 (eight maturities from one to thirty years), the first three components explain 85.1%, 11.0% and 2.1% of the variance, 98.2% together, with daily standard deviations of 13.6, 4.9 and 2.1 basis points of score (Figure 3.3). The level loads less on the one-year than on the belly; the curvature factor is dominated by the one-year yield, the maturity most tied to the next policy meetings. Litterman and Scheinkman found the same three factors in 1991.