
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Leverage rebalancing flow؟

Definition 26.2 Strategies I: Equities and Futures · الفصل 26 — Volatility Targeting and Risk-Managed Portfolios

A leverage rebalancing flow is the net trading of portfolios that follow mechanical exposure rules (volatility targets, leveraged funds’ daily resets, risk parity) in response to price and volatility changes; because many follow similar rules, the flow is concentrated and predictable from the rules and the market’s recent moves.
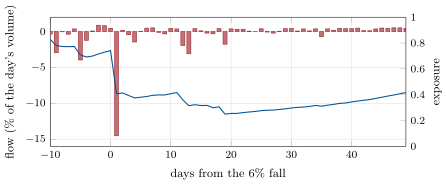
Volatility-targeting funds around a synthetic 6% fall: their net flow as a share of each day’s volume (bars, left) and their exposure (line, right). Funds hold 0.2% of the market’s value and the market trades 0.4% of its value a day (assumed). Data: s1_voltarget.spike.
Figure 26.2. Volatility-targeting funds around a synthetic 6% fall: their net flow as a share of each day’s volume (bars, left) and their exposure (line, right). Funds hold 0.2% of the market’s value and the market trades 0.4% of its value a day (assumed). Data: s1_voltarget.spike.
اقرأ في الفصل →