
सभी किताबें

पेशेवर

ऐप्स परिचय Coach लॉग इन पढ़ना शुरू करें

Quantitative Finance · शब्दावली

Leverage rebalancing flow क्या है?

Definition 26.2 Strategies I: Equities and Futures · अध्याय 26 — Volatility Targeting and Risk-Managed Portfolios

A leverage rebalancing flow is the net trading of portfolios that follow mechanical exposure rules (volatility targets, leveraged funds’ daily resets, risk parity) in response to price and volatility changes; because many follow similar rules, the flow is concentrated and predictable from the rules and the market’s recent moves.
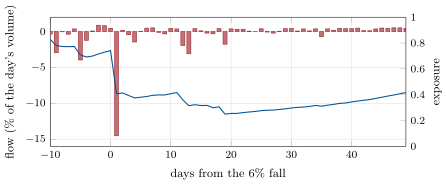
Volatility-targeting funds around a synthetic 6% fall: their net flow as a share of each day’s volume (bars, left) and their exposure (line, right). Funds hold 0.2% of the market’s value and the market trades 0.4% of its value a day (assumed). Data: s1_voltarget.spike.
Figure 26.2. Volatility-targeting funds around a synthetic 6% fall: their net flow as a share of each day’s volume (bars, left) and their exposure (line, right). Funds hold 0.2% of the market’s value and the market trades 0.4% of its value a day (assumed). Data: s1_voltarget.spike.
अध्याय में पढ़ें →