
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Likelihood-ratio Greek؟

Definition 23.8 Derivatives and Volatility · الفصل 23 — Monte Carlo Pricers in Practice

A likelihood-ratio Greek differentiates the density of the simulated state instead of the payoff: it averages the discounted payoff times the score, the derivative of the log-density with respect to the parameter; it works for discontinuous payoffs, at the cost of a higher variance.
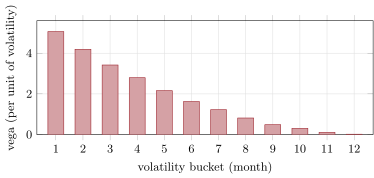
Bucketed vegas of a one-year arithmetic Asian call from one adjoint pass along each path: the average’s sensitivity to early volatility is largest because early moves carry through every later fixing. Data: the tutorial.
Figure 23.3. Bucketed vegas of a one-year arithmetic Asian call from one adjoint pass along each path: the average’s sensitivity to early volatility is largest because early moves carry through every later fixing. Data: the tutorial.

أمثلة

Example 23.9 (Twelve vegas for the price of three passes)

An arithmetic Asian call (one year, 48 steps, strike 100, 20%) is priced along with its sensitivity to the volatility in each of twelve monthly buckets. Forward mode would need one pass per bucket. The adjoint (reverse) pass of One Quant Book 4, chapter 28, runs once backwards along each stored path and accumulates the derivative of the payoff with respect to every step’s state and volatility. It returns all twelve vegas and the delta at a cost of a few forward passes. The price is 5.901 and the delta 0.593. The vega of the first month is 5.064, where bumping that month’s volatility with the same draws gives 5.065, and the vegas fall to 0.016 for the last month (Figure 23.3).

اقرأ في الفصل →