Todos los libros

Profesional

Apps Acerca de Coach Iniciar sesión Empezar a leer

Quantitative Finance · Glosario

¿Qué es Maximum drawdown, drawdown duration, Calmar ratio?

También llamado: maximum drawdown · drawdown duration · Calmar ratio

Definition 22.4 Research Craft: Predictors, Backtests, Measurement, Portfolios · Capítulo 22 — Performance Measurement

The maximum drawdown of a history is its largest fall of wealth from a running peak, as a fraction of the peak (drawdown: Book 2, chapter 29). The drawdown duration of a spell is the time from the peak to the recovery of that peak, or to the end of the history if it has not recovered. The Calmar ratio is the annualised return over the absolute maximum drawdown, traditionally on three years.
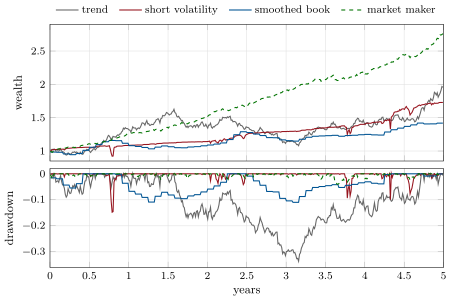
The four displayed five-year histories: wealth (top) and drawdown from the running peak (bottom). The smoothed book is monthly and drawn as steps of a month. Data: rs_perf.histories.
Figure 22.1. The four displayed five-year histories: wealth (top) and drawdown from the running peak (bottom). The smoothed book is monthly and drawn as steps of a month. Data: rs_perf.histories.
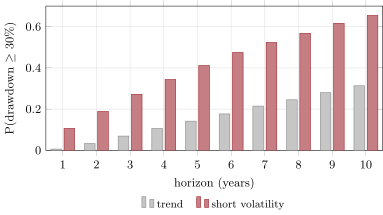
The probability of a drawdown of 30% or more within a horizon, over 4 000 simulated paths of each strategy’s model (long-run volatilities of 15% and 17%). Data: rs_perf.dd_probability.
Figure 22.2. The probability of a drawdown of 30% or more within a horizon, over 4 000 simulated paths of each strategy’s model (long-run volatilities of 15% and 17%). Data: rs_perf.dd_probability.
Leer en el capítulo →