सभी किताबें

पेशेवर

ऐप्स परिचय Coach लॉग इन पढ़ना शुरू करें

Quantitative Finance · शब्दावली

Minimum-variance delta क्या है?

Definition 11.6 Derivatives and Volatility · अध्याय 11 — SABR and Smile Dynamics

The minimum-variance delta of an option in a stochastic volatility model is the position in the underlying that minimises the variance of the hedged position’s instantaneous P&L. In SABR (Bartlett’s delta) it is

ΔMV=ΔBS+V(∂σB∂F+∂σB∂α ρνFβ).\Delta_{\mathrm{MV}}=\Delta_{\mathrm{BS}}+\mathcal V\Bigl(\frac{\partial\sigma_B}{\partial F} +\frac{\partial\sigma_B}{\partial\alpha}\,\frac{\rho\nu}{F^{\beta}}\Bigr).
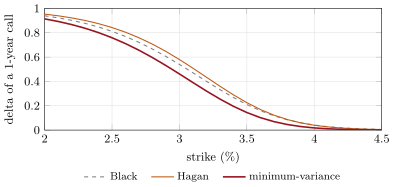
Three deltas of one-year calls on a 3% forward by strike (=0.5, =-0.6, =0.5). The minimum-variance delta is the smallest, because a rise in the forward is expected to come with a fall in volatility. Data: the tutorial.
Figure 11.3. Three deltas of one-year calls on a 3% forward by strike (β=0.5\beta=0.5, ρ=−0.6\rho=-0.6, ν=0.5\nu=0.5). The minimum-variance delta is the smallest, because a rise in the forward is expected to come with a fall in volatility. Data: the tutorial.
अध्याय में पढ़ें →