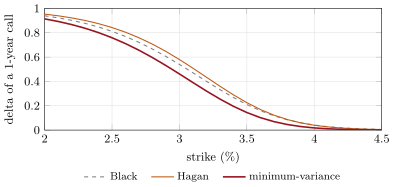
The minimum-variance delta of an option in a stochastic volatility model is the position in the underlying that minimises the variance of the hedged position’s instantaneous P&L. In SABR (Bartlett’s delta) it is
 Pelatih
Masuk
Mulai membaca
Quantitative Finance · Glosarium
The minimum-variance delta of an option in a stochastic volatility model is the position in the underlying that minimises the variance of the hedged position’s instantaneous P&L. In SABR (Bartlett’s delta) it is