Tous les livres

Professionnel

Applis À propos Coach Connexion Commencer la lecture

Quantitative Finance · Glossaire

Qu'est-ce que « Moving-average crossover, linear filter » ?

Aussi appelé : moving-average crossover · linear filter

Definition 7.6 Research Craft: Predictors, Backtests, Measurement, Portfolios · Chapitre 7 — Price and Volume Features

A moving-average crossover with windows n<mn < m is the logarithm of the ratio of the average of the last nn prices to the average of the last mm prices; the classic rule is long when it is positive. A linear filter of returns is a predictor of the form ∑j≥0wjrt−j\sum_{j \ge 0} w_jr_{t-j} with fixed weights wjw_j.

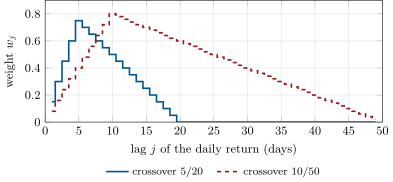
Weights a moving-average crossover puts on each past daily return (): rising over the short window, then falling linearly to zero at the long window. The 5/20 crossover sums to 7.5 and peaks at lag 5; the 10/50 to 20 and peaks at lag 10.
Figure 7.3. Weights a moving-average crossover puts on each past daily return (Proposition 7.7): rising over the short window, then falling linearly to zero at the long window. The 5/20 crossover sums to 7.5 and peaks at lag 5; the 10/50 to 20 and peaks at lag 10.
Lire dans le chapitre →