
All books

Professional

Apps About Coach Log in Start reading

Quantitative Finance · Glossary

What is Option-adjusted spread?

Definition 21.6 Markets II: Rates, FX and Credit · Chapter 21 — Corporate Bonds

The option-adjusted spread (OAS) of a bond with embedded options is the spread over the curve at which the bond’s value, computed with a model of rates that values the options, equals its price: the Z-spread less the options’ cost expressed as a spread.
Ten-year high-quality corporate spot rate (Treasury HQM curve, bonds rated AAA, AA or A) minus the ten-year Treasury yield, monthly, 1984 to August 2026. The measure mixes credit with the difference between a zero-coupon and a par rate, but its peaks, 2008 and 2020, are the credit crises. Data: FRED series HQMCB10YR (US Treasury) and GS10.
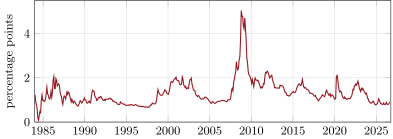
Figure 21.3. Ten-year high-quality corporate spot rate (Treasury HQM curve, bonds rated AAA, AA or A) minus the ten-year Treasury yield, monthly, 1984 to August 2026. The measure mixes credit with the difference between a zero-coupon and a par rate, but its peaks, 2008 and 2020, are the credit crises. Data: FRED series HQMCB10YR (US Treasury) and GS10.
Read in context →