 Coach
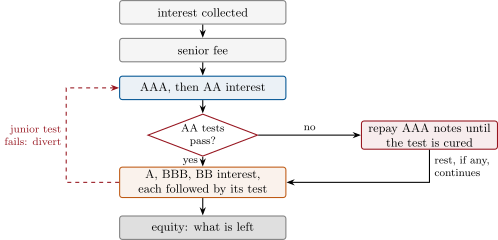
An overcollateralisation test compares the par value of the loans with the notes outstanding down to a given class; an interest-coverage test compares the interest collected with the interest due on those notes. Each has a trigger ratio, and when a ratio falls below it, cash that would have gone further down the waterfall repays the most senior notes instead. The equity tranche of a securitisation is its most junior claim, unrated, which receives whatever cash is left after every other claim has been paid.
Voorbeelden
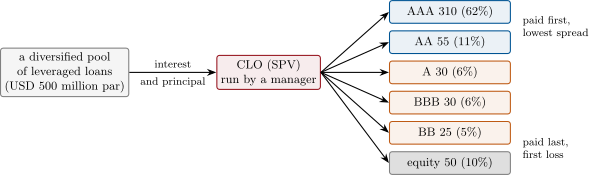
Example 25.5 (The excess spread)
The chapter’s CLO holds USD 500 million of loans paying 3.5% over a floating rate of 4%, USD 37.5 million a year. The manager’s fee of 0.45% costs USD 2.25 million, and the notes, from AAA at 1.30% over to BB at 6.00% over, cost USD 26.14 million. The equity, USD 50 million, receives USD 9.11 million a year, 18.2% of its investment; without defaults and with the loans sold at par after five years, its internal rate of return is 19.5%. The overcollateralisation ratios start at 1.370, 1.266, 1.176 and 1.111 at the AA, A, BBB and BB levels, against triggers of 1.25, 1.18, 1.10 and 1.05.