 Pelatih
The point of non-viability is the moment an authority decides that a bank would fail without a write-down of its capital instruments or public support. A bail-in is the write-down or conversion into equity of a failing bank’s liabilities by an authority, so that creditors instead of taxpayers bear its losses.
Contoh
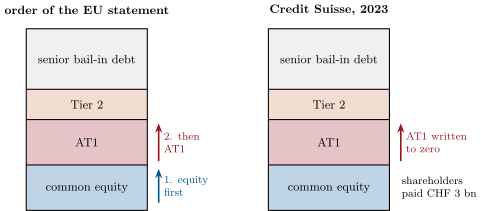
Example 26.9 (Two orders of loss)
An illustrative bank has 45 of common equity, 16 of AT1, 12 of Tier 2 and 80 of senior debt eligible for bail-in, in billions. A loss of 20 absorbed in the order of the EU statement leaves equity with 25 and every bond intact. An AT1 write-down under a contractual trigger removes all 16 of the AT1 and leaves the equity with 45.