All books

Professional

Apps About Coach Log in Start reading

Quantitative Finance · Glossary

What is Principal component analysis, minimum-variance portfolio?

Also known as: principal component analysis · minimum-variance portfolio

Definition 22.2 Quantitative Methods · Chapter 22 — Covariance Estimation and Random Matrices

Principal component analysis diagonalises a covariance (or correlation) matrix, S=UΛU⊤S = U\Lambda U^\top: the eigenvectors are uncorrelated portfolios and the eigenvalues their variances, in decreasing order. The minimum-variance portfolio for a covariance Σ\Sigma is w=Σ−11/(1⊤Σ−11)w = \Sigma^{-1}\mathbf 1/(\mathbf 1^\top\Sigma^{-1}\mathbf 1), the fully invested portfolio of smallest variance, 1/(1⊤Σ−11)1/(\mathbf 1^\top\Sigma^{-1}\mathbf 1).

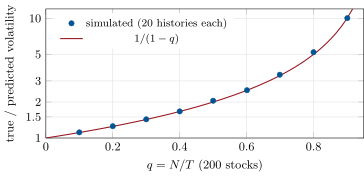
Ratio of the true to the predicted volatility of the sample minimum-variance portfolio of 200 stocks, against q = N/T (histories from 2 000 to 222 days), and the high-dimensional formula 1/(1 - q). Data: the chapter’s tutorial, seeded.
Figure 22.1. Ratio of the true to the predicted volatility of the sample minimum-variance portfolio of 200 stocks, against q=N/Tq = N/T (histories from 2 000 to 222 days), and the high-dimensional formula 1/(1−q)1/(1 - q). Data: the chapter’s tutorial, seeded.
Read in context →