المدرب
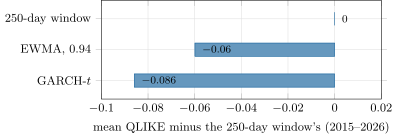
The QLIKE loss is (up to terms that do not involve ), the negative Gaussian log-likelihood of the proxy’s return: minimised in expectation by and heavier on under-prediction than on over-prediction. The Mincer–Zarnowitz regression (1969) of the proxy on the forecast, , tests unbiasedness (, ). The Diebold–Mariano test (1995) of equal accuracy divides the mean loss difference of two forecasts by its HAC standard error.