
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Quadratic-exponential scheme؟

Definition 23.1 Derivatives and Volatility · الفصل 23 — Monte Carlo Pricers in Practice

The quadratic-exponential scheme (QE) simulates Heston’s variance over a step by matching the mean mm and variance s2s^2 of its exact conditional law: when ψ=s2/m2\psi=s^2/m^2 is small it draws a(b+Z)2a(b+Z)^2, a scaled non-central square of a normal; when ψ\psi is large, a mixture of a mass at zero and an exponential. The log-price then uses the integrated variance implied by the start and end variances.
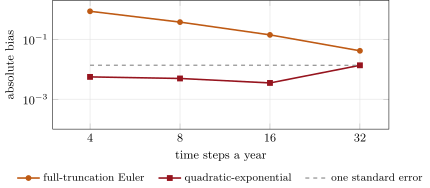
Bias of a one-year at-the-money call in a Heston model whose variance can reach zero, by time steps, against the Fourier price (400 000 paths). Euler’s bias decays slowly; QE’s stays within the statistical error at every step count. Data: the tutorial.
Figure 23.1. Bias of a one-year at-the-money call in a Heston model whose variance can reach zero, by time steps, against the Fourier price (400 000 paths). Euler’s bias decays slowly; QE’s stays within the statistical error at every step count. Data: the tutorial.

أمثلة

Example 23.2 (Euler against QE)

A one-year at-the-money call in chapter 10’s base Heston model (v0=vˉ=0.04v_0=\bar v=0.04, κ=1.5\kappa=1.5, η=0.6\eta=0.6, ρ=−0.7\rho=-0.7) is worth 6.751 by Fourier inversion. With 400 000 paths and full-truncation Euler, the bias is 0.857 with 4 steps a year, 0.373 with 8, 0.140 with 16 and 0.041 with 32. With QE the price is within one standard error (0.014) of the exact value at every step count, from 4 steps a year (Figure 23.1). QE saves a factor of ten or more in steps, and so in run time.

اقرأ في الفصل →