 Coach
The quadratic-exponential scheme (QE) simulates Heston’s variance over a step by matching the mean and variance of its exact conditional law: when is small it draws , a scaled non-central square of a normal; when is large, a mixture of a mass at zero and an exponential. The log-price then uses the integrated variance implied by the start and end variances.
उदाहरण
Example 23.2 (Euler against QE)
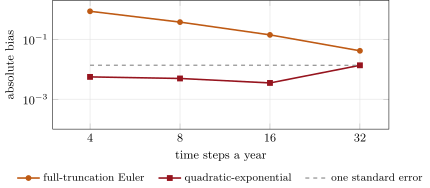
A one-year at-the-money call in chapter 10’s base Heston model (, , , ) is worth 6.751 by Fourier inversion. With 400 000 paths and full-truncation Euler, the bias is 0.857 with 4 steps a year, 0.373 with 8, 0.140 with 16 and 0.041 with 32. With QE the price is within one standard error (0.014) of the exact value at every step count, from 4 steps a year (Figure 23.1). QE saves a factor of ten or more in steps, and so in run time.