Todos os livros

Profissional

Apps Sobre Coach Entrar Começar a ler

Quantitative Finance · Glossário

O que é Rannacher time-stepping?

Definition 27.7 Quantitative Methods · Capítulo 27 — Finite-Difference Methods

Rannacher time-stepping (Rannacher, 1984) replaces the first Crank–Nicolson steps by implicit Euler steps of half the size, which damp the high frequencies of non-smooth initial data, and continues with Crank–Nicolson.
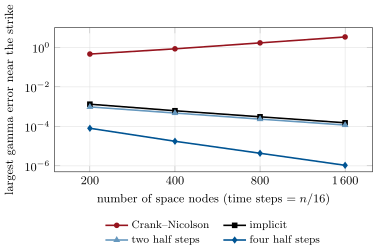
Largest gamma error of the three-month call for 90 < S < 110 as space and time are refined together: plain Crank–Nicolson diverges, the implicit scheme and Crank–Nicolson with two implicit half steps converge at first order, and with four at second order. Data: the chapter’s tutorial.
Figure 27.3. Largest gamma error of the three-month call for 90<S<11090 < S < 110 as space and time are refined together: plain Crank–Nicolson diverges, the implicit scheme and Crank–Nicolson with two implicit half steps converge at first order, and with four at second order. Data: the chapter’s tutorial.
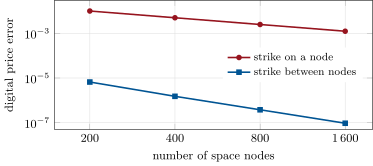
Price error of a three-month digital at the strike, Crank–Nicolson with four implicit half steps: the strike on a node gives first order, the strike midway between nodes second order. Data: the chapter’s tutorial.
Figure 27.4. Price error of a three-month digital at the strike, Crank–Nicolson with four implicit half steps: the strike on a node gives first order, the strike midway between nodes second order. Data: the chapter’s tutorial.
Ler no capítulo →
