
All books

Professional

Apps About Coach Log in Start reading

Quantitative Finance · Glossary

What is Realised kernel, pre-averaging estimator?

Also known as: realised kernel · pre-averaging estimator

Definition 21.6 Quantitative Methods · Chapter 21 — High-Frequency Econometrics

A realised kernel (Barndorff-Nielsen, Hansen, Lunde and Shephard, 2008) adds weighted autocovariances of the high-frequency returns to their variance, γ0+∑h=1Hk(h−1H)(γh+γ−h)\gamma_0 + \sum_{h=1}^Hk\bigl(\frac{h-1}H\bigr)(\gamma_h + \gamma_{-h}), with a smooth weight such as Parzen’s, to cancel the negative autocovariance the noise creates. The pre-averaging estimator (Jacod, Li, Mykland, Podolskij and Vetter, 2009) averages returns over short overlapping windows with a weight function, which shrinks the noise in each window, then squares and rescales the averages and subtracts the remaining bias.
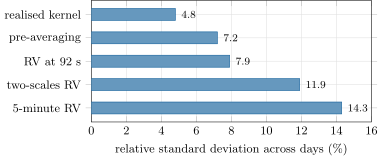
Precision of five daily volatility estimators on the simulated stock’s trade prices, thirty days: the standard deviation of the daily estimate relative to the true integrated variance. All are nearly unbiased (average volatilities between 25.1% and 25.8% for a true 25%). Data: the chapter’s tutorial, seeded.
Figure 21.3. Precision of five daily volatility estimators on the simulated stock’s trade prices, thirty days: the standard deviation of the daily estimate relative to the true integrated variance. All are nearly unbiased (average volatilities between 25.1% and 25.8% for a true 25%). Data: the chapter’s tutorial, seeded.
Read in context →