Pelatih
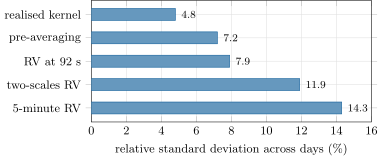
A realised kernel (Barndorff-Nielsen, Hansen, Lunde and Shephard, 2008) adds weighted autocovariances of the high-frequency returns to their variance, , with a smooth weight such as Parzen’s, to cancel the negative autocovariance the noise creates. The pre-averaging estimator (Jacod, Li, Mykland, Podolskij and Vetter, 2009) averages returns over short overlapping windows with a weight function, which shrinks the noise in each window, then squares and rescales the averages and subtracts the remaining bias.