
Todos los libros

Profesional

Apps Acerca de Coach Iniciar sesión Empezar a leer

Quantitative Finance · Glosario

¿Qué es Residual risk hedge?

Definition 25.3 Strategies II: Volatility, Relative Value, Macro and the Bank Desks · Capítulo 25 — The Central Risk Book

A residual risk hedge hedges a pooled book’s exposure to common factors at once with liquid instruments (index futures, factor baskets) and leaves the remaining, mostly idiosyncratic, positions to be traded out gradually or offset by later flows.
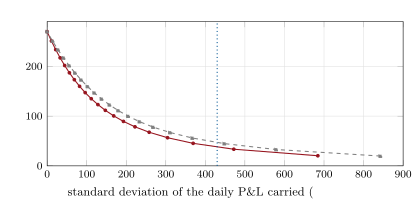
The central book’s cost-risk frontier as the share of inventory traded out each day runs from 5% to 100%, with and without an index-future overlay; the dotted line is the standard deviation at which the one-day 99% value at risk reaches $1 million. Data: s2_crbook.frontier.
Figure 25.2. The central book’s cost-risk frontier as the share of inventory traded out each day runs from 5% to 100%, with and without an index-future overlay; the dotted line is the standard deviation at which the one-day 99% value at risk reaches $1 million. Data: s2_crbook.frontier.
Leer en el capítulo →