 Coach
A residual risk hedge hedges a pooled book’s exposure to common factors at once with liquid instruments (index futures, factor baskets) and leaves the remaining, mostly idiosyncratic, positions to be traded out gradually or offset by later flows.
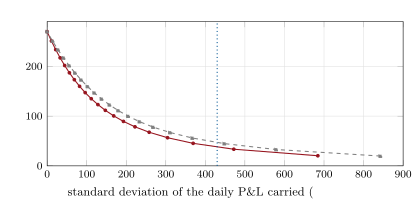
s2_crbook.frontier.