Coach
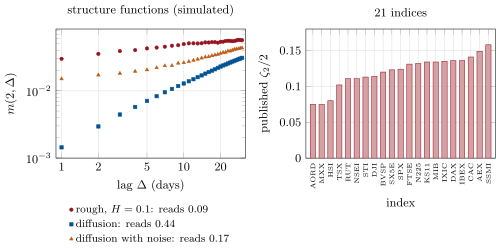
Rough volatility is the property, and the class of models built on it, that the logarithm of instantaneous volatility behaves at short time scales like a fractional Brownian motion with Hurst exponent , typically near 0.1. Its paths are rougher than any diffusion’s: the typical move over a lag scales like rather than .