
All books

Professional

Apps About Coach Log in Start reading

Quantitative Finance · Glossary

What is Sandwich variance?

Definition 11.7 Quantitative Methods · Chapter 11 — Estimation

The sandwich variance of an estimator defined by an estimating equation is A−1BA−1A^{-1}BA^{-1}: the bread AA, the expected derivative of the estimating equation, around the meat BB, the variance of the equation itself. Estimated by the sample Hessian and the outer product of the per-observation scores, it is the robust (Huber–White) variance.
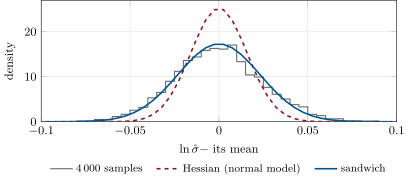
The log standard deviation estimated by a normal likelihood from 2 000 Student-t_6 observations: its actual sampling distribution (steps) against the normal approximations with the Hessian standard error (dashed), too narrow, and with the sandwich (solid). Data: the chapter’s tutorial, seeded.
Figure 11.1. The log standard deviation estimated by a normal likelihood from 2 000 Student-t6t_6 observations: its actual sampling distribution (steps) against the normal approximations with the Hessian standard error (dashed), too narrow, and with the sandwich (solid). Data: the chapter’s tutorial, seeded.
Read in context →