 Coach
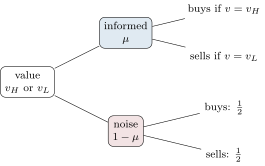
A sequential-trade model lets traders arrive one at a time to a competitive, risk-neutral liquidity provider who quotes before each arrival and learns from each trade. The Glosten–Milgrom model is the sequential-trade model in which each arrival is informed with probability and trades in the direction of the value, or is a noise trader who buys or sells with equal probability, and the provider sets the ask and bid to the expected value conditional on a buy and on a sale.
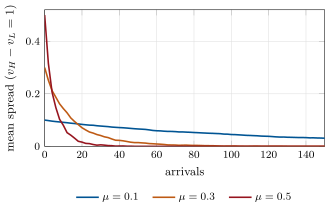
mx_spread.gm_learning.