
सभी किताबें

पेशेवर

ऐप्स परिचय Coach लॉग इन पढ़ना शुरू करें

Quantitative Finance · शब्दावली

Short-volatility strategy क्या है?

Definition 1.1 Strategies II: Volatility, Relative Value, Macro and the Bank Desks · अध्याय 1 — Harvesting the Variance Risk Premium

A short-volatility strategy earns the variance risk premium by selling options or variance and delivering realised volatility: short variance swaps, delta-hedged short options, covered calls, short puts, or short volatility futures. Its returns are small and frequent in calm markets and large and negative when volatility jumps.
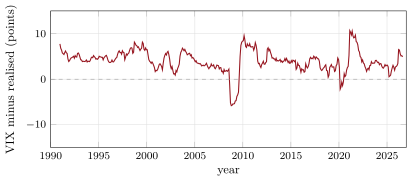
The S&P 500 variance premium, 1990–2026: the twelve-month average, at each month-end, of the VIX minus the realised volatility of the S&P 500 over the following 21 trading days. Derived from Cboe’s VIX and S&P 500 index histories; the raw series are not redistributed. Data: s2_fetch_cboe.
Figure 1.1. The S&P 500 variance premium, 1990–2026: the twelve-month average, at each month-end, of the VIX minus the realised volatility of the S&P 500 over the following 21 trading days. Derived from Cboe’s VIX and S&P 500 index histories; the raw series are not redistributed. Data: s2_fetch_cboe.
अध्याय में पढ़ें →