Semua buku

Profesional

Aplikasi Tentang Pelatih Masuk Mulai membaca

Quantitative Finance · Glosarium

Apa itu Swaption matrix?

Definition 5.6 Rates, Credit, XVA and Risk · Bab 5 — SABR in Rates and the Volatility Cube

The swaption matrix of a currency is the table of at-the-money swaption volatilities by option expiry and underlying swap tenor: the at-the-money face of the volatility cube (One Quant Book 2, chapter 13).
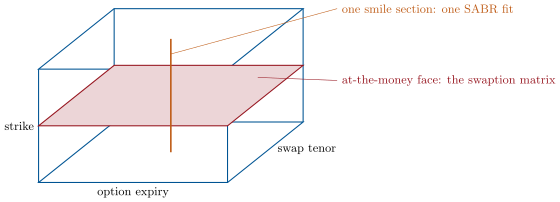
The volatility cube: a smile for each (expiry, tenor). The at-the-money face is the swaption matrix; each vertical line is a section calibrated with its own SABR parameters,  and the shift being fixed for the whole currency.
Figure 5.2. The volatility cube: a smile for each (expiry, tenor). The at-the-money face is the swaption matrix; each vertical line is a section calibrated with its own SABR parameters, β\beta and the shift being fixed for the whole currency.
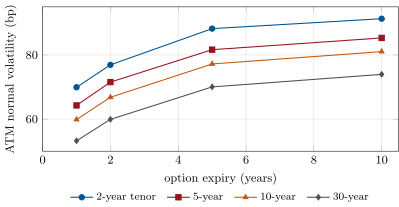
The swaption matrix of the synthetic cube: at-the-money normal volatility of the calibrated sections by expiry, one line per tenor. Data: the chapter’s tutorial.
Figure 5.3. The swaption matrix of the synthetic cube: at-the-money normal volatility of the calibrated sections by expiry, one line per tenor. Data: the chapter’s tutorial.
Baca dalam konteks →
