
جميع الكتب

مهني

1 Markets I: The Ecosystem and Exchange-Traded Marketsالأسواق عبر الإنترنت 2 Markets II: Rates, FX and Creditالأسواق عبر الإنترنت 3 Markets III: Commodities, Energy and Cryptoالأسواق عبر الإنترنت 4 Quantitative Methodsالأساليب عبر الإنترنت 5 Derivatives and Volatilityالمشتقات عبر الإنترنت 6 Rates, Credit, XVA and Riskالفائدة والائتمان والمخاطر عبر الإنترنت 7 Research Craft: Predictors, Backtests, Measurement, Portfoliosالبحث عبر الإنترنت 8 Strategies I: Equities and Futuresالاستراتيجيات عبر الإنترنت 9 Strategies II: Volatility, Relative Value, Macro and the Bank Desksالاستراتيجيات عبر الإنترنت 10 Microstructure and Executionالتنفيذ عبر الإنترنت 11 Market Making and High-Frequency Tradingصناعة السوق عبر الإنترنت 12 Machine Learning for Marketsتعلم الآلة عبر الإنترنت 13 Low-Latency Softwareالتكنولوجيا عبر الإنترنت 14 Networks, Hardware and Trading Infrastructureالتكنولوجيا عبر الإنترنت 15 Research, Data and Risk Platformsالتكنولوجيا عبر الإنترنت 16 The Desk and the Firmالشركة عبر الإنترنت 17 The Industry: Firms, Roles and Careersالمسارات المهنية عبر الإنترنت 18 The Interview Bookالمسارات المهنية عبر الإنترنت
التطبيقات حول المدرب تسجيل الدخول ابدأ القراءة

Quantitative Finance · المسرد

ما معنى Traffic-light test؟

Definition 21.16 Rates, Credit, XVA and Risk · الفصل 21 — Market-Risk Measures

The traffic-light test classifies a 99% VaR model by its exceptions over 250 days: green for 0 to 4, yellow for 5 to 9 with increases of 0.40, 0.50, 0.65, 0.75 and 0.85 in the capital multiplication factor of 3, red for 10 or more (an increase of 1). Under the 1996 rules, capital is the higher of the previous day’s ten-day VaR and the factor times its average over the preceding sixty business days.
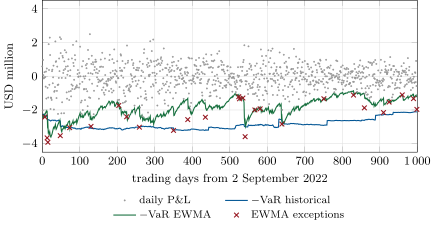
Four years of the book’s daily P&L against the negative of the previous day’s 99% VaR from historical simulation and from the EWMA delta-normal model; crosses mark the EWMA model’s exceptions. The EWMA line reacts to volatility quickly but runs too close to zero for fat-tailed days. Data: US Treasury, ECB; the chapter’s tutorial.
Figure 21.3. Four years of the book’s daily P&L against the negative of the previous day’s 99% VaR from historical simulation and from the EWMA delta-normal model; crosses mark the EWMA model’s exceptions. The EWMA line reacts to volatility quickly but runs too close to zero for fat-tailed days. Data: US Treasury, ECB; the chapter’s tutorial.

أمثلة

Example 21.17 (Four years of backtesting)

Recomputing each model every day from 2 September 2022 to 23 September 2026, on the same book revalued at each day’s levels, against the next day’s P&L: historical simulation has 10 exceptions in 1 000 days (Kupiec p-value 1.00) and none in the last 250, green; the EWMA delta-normal model has 28 (Kupiec likelihood ratio 22.0, p-value 3×10−63\times10^{-6}) and 8 in the last 250, yellow with a 0.75 increase; filtered historical simulation has 8 and 3, green (Figure 21.3). None fails the independence test at 5%.

اقرأ في الفصل →