Alle boeken

Professioneel

Apps Over Coach Inloggen Begin met lezen

Quantitative Finance · Begrippenlijst

Wat is Triple-barrier label?

Definition 2.2 Machine Learning for Markets · Hoofdstuk 2 — Targets, Labels and Sample Weights

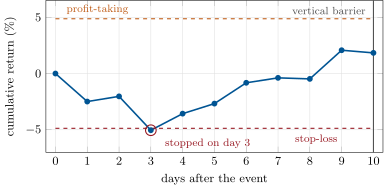
For an event at t0t_0 with position side ±1\pm1, widths w+,w−>0w^+, w^- > 0 and a horizon hh, the triple-barrier label settles at the first bar t1t_1 at which the position’s cumulative log return reaches +w++w^+ (profit-taking), −w−-w^- (stop-loss), or t1=t0+ht_1 = t_0 + h (the vertical barrier); it is the sign of the position’s return at t1t_1. The widths are usually scaled by the volatility known at t0t_0: w=kσ^t0hw = k\hat\sigma_{t_0}\sqrt h (López de Prado, 2018).

One event of asset 0, a long position: the barriers are one ten-day volatility, 4.87%, known at the event. The stop is touched on day three; the ten-day return ends at +1.84\%. Data: firm.mlsynth.series, seed 1, through firm.labeling.triple_barrier.
Figure 2.1. One event of asset 0, a long position: the barriers are one ten-day volatility, 4.87%, known at the event. The stop is touched on day three; the ten-day return ends at +1.84%+1.84\%. Data: firm.mlsynth.series, seed 1, through firm.labeling.triple_barrier.
Lees in het hoofdstuk →