
Alle boeken

Professioneel

Apps Over Coach Inloggen Begin met lezen

Quantitative Finance · Begrippenlijst

Wat is Turn-of-the-month effect?

Definition 23.2 Strategies I: Equities and Futures · Hoofdstuk 23 — Seasonality and Calendar Effects

The turn-of-the-month effect is the tendency of stock market returns to be higher on the last trading day of a month and the first few days of the next than on other days; month-end flows (salaries, pension contributions and fund rebalancing invested at the start of the month) are the candidate mechanism.
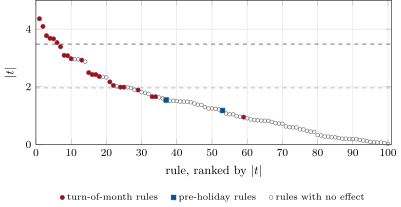
A hundred calendar rules tested on thirty years of the synthetic equity class with two planted effects: the absolute t-statistic of each rule, ranked, by what it carries. The lower dashed line is the uncorrected 5% threshold (1.96), the upper one Bonferroni’s for a hundred tests (3.48). Data: s1_seasonal.calendar_test.
Figure 23.2. A hundred calendar rules tested on thirty years of the synthetic equity class with two planted effects: the absolute t-statistic of each rule, ranked, by what it carries. The lower dashed line is the uncorrected 5% threshold (1.96), the upper one Bonferroni’s for a hundred tests (3.48). Data: s1_seasonal.calendar_test.
Lees in het hoofdstuk →